The Strategic Shift: Why Semi-Commercial Property is Reshaping the BTL Market in the UK
 Written by Darrell Walker
The UK property investment landscape is undergoing one of its most significant structural evolutions in decades. As macroeconomic shifts, tightening fiscal policy and regulatory developments reshape the private rental sector, property investors are fundamentally re-evaluating their asset strategies. Traditional, single-tenant residential buy-to-let (BTL) properties, long considered the standard choice for private property portfolios, are increasingly facing margin pressures, with typical gross residential yield sitting between 5 and 6%.
In response, professional landlords and investors are looking beyond single residential units to target higher-yielding, multi-stream asset classes. At the forefront of this shift is the semi-commercial property market, a dynamic offering that combines commercial enterprise with residential living under a single title to deliver enhanced cash flow, operational resilience and strong tax-efficient growth potential.
This pivot toward mixed-use assets is backed by market momentum and sustained volume growth. Total UK commercial lending is projected to reach £118 billion by 2028, with semi-commercial assets driving a significant portion of this expansion as they move from a niche strategy into a permanent fixture of modern portfolio design. Following a landmark year in 2024 where application volumes doubled, semi-commercial properties captured 24% of all commercial lending activity. Investor appetite accelerated further into 2025, with applications climbing an additional 58% year-on-year and purchase applications rising 31% as a proportion of overall specialist lending.
Underpinned by a tight private rental sector where property availability sits 18% below tenant demand, retail units with residential flats above now represent 69% of all mixed-use applications, proving that appetite for resilient, dual-income assets has firmly entered the mainstream.
The Dual-Engine Advantage: Yield and Risk Mitigation
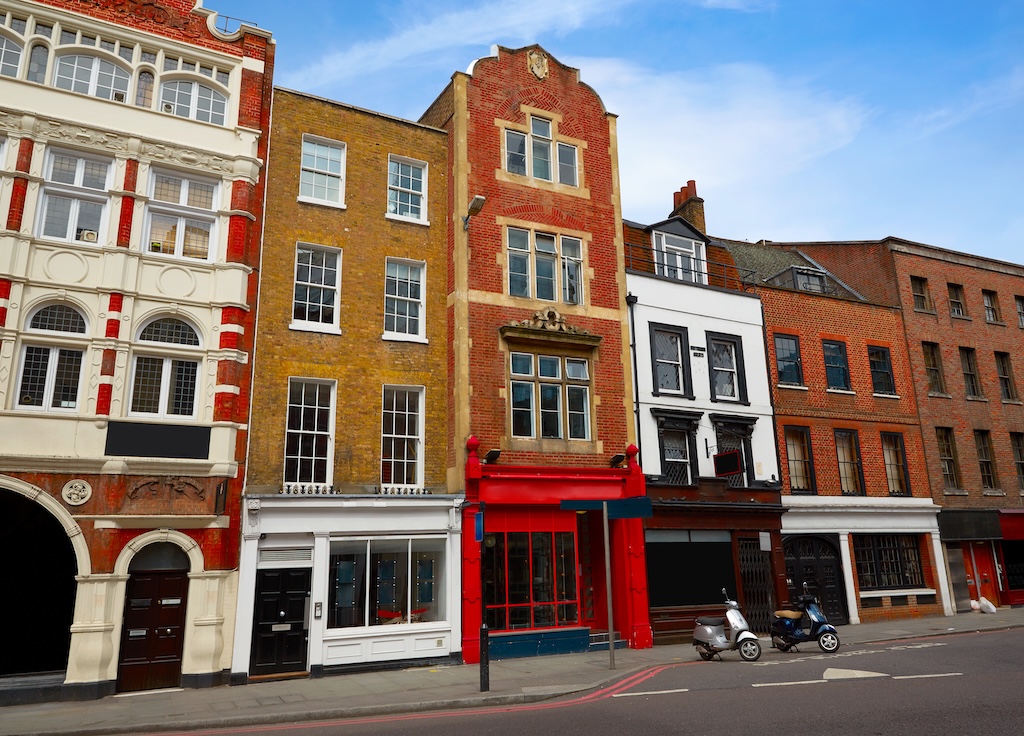
At its core, a semi-commercial asset, most commonly a ground-floor retail or service business with residential flats above, offers a compelling economic proposition. Rather than relying on a single tenancy, investors capture two distinct revenue channels within a single property.
This dual-stream mechanism provides strategic advantages:
- Yield Premium: Semi-commercial properties routinely deliver gross yields between 8% and 10.5%, significantly outperforming standard single-let residential assets. In regional commercial hubs and regenerating high streets, well-structured mixed-use units represent some of the most lucrative income opportunities in the UK property market.
- Risk Diversification: Prolonged void periods pose a major threat to investor profitability. By pairing commercial occupiers on long-term leases with residential tenants on standard rental agreements, investors can mitigate the risk of total income loss. If one component is vacant, the secondary revenue stream continues to service debt and cover holding costs.
- Tax and SDLT Efficiencies: A major catalyst behind the capital shift into mixed-use assets relates to Stamp Duty Land Tax (SDLT). Because semi-commercial properties qualify as mixed-use assets, they fall under commercial SDLT rate bands rather than the higher residential bands and surcharges. This difference can substantially reduce entry costs, leaving investors with higher working capital and better returns.
Semi-commercial BTL lending made simple
Capitalising on High Street Evolution
The momentum behind semi-commercial assets is also closely linked to the transformation of UK regional town centres and local high streets. Far from the idea of commercial decline, high streets across the country are being actively re-energised.
Ground-floor commercial units are increasingly occupied by neighbourhood-centric, essential businesses like independent cafés, convenience stores, service providers and health centres. The commercial occupiers act as reliable economic anchors. At the same time, tenant demand for centrally located, urban residential space remains exceptionally strong due to underlying housing shortages. By acquiring and upgrading mixed-use buildings, investors actively contribute to local urban regeneration while securing high-demand rental units.
Financing Flexibility and Portfolio Professionalisation
The rising interest in semi-commercial real estate reflects a broader trend toward professionalisation in the investor market. Landlords are operating with a structured, corporate mindset, utilising Limited Companies, Special Purpose Vehicles (SPVs) and professional management models to optimise their holdings.
Debt strategies for mixed-use properties have adapted alongside this market maturity. Investors will often utilise short-term refurbishment or bridging facilities to upgrade commercial units, convert unused upper-floor storage into residential accommodation or improve Energy Performance Certificate (EPC) ratings. Once value-add works are completed, investors can transition onto long-term BTL term finance or execute equity releases to fuel further acquisitions.
As the UK property market demands greater adaptability and stronger margins, semi-commercial BTL has evolved from a specialist strategy into a mainstream growth pillar. By offering higher baseline yields, dual-income safety nets and lower acquisition tax barriers, mixed-use properties provide modern investors with the precise balance of income and resilience needed to construct scalable and future-proof portfolios.
Navigating these hybrid transactions requires a nuanced approach that traditional mainstream lenders often struggle to deliver. From balancing commercial leases alongside standard residential tenancy agreements to underwriting corporate structures and mixed-use valuations, semi-commercial assets carry unique operational complexities. This is precisely where specialist lenders excel, offering the bespoke underwriting, sector-specific expertise and structural flexibility needed to evaluate complex transactions efficiently.
By aligning with specialist lenders (like LendInvest) that truly understand the distinct dynamics of mixed-use real estate, investors and brokers can seamlessly navigate structural nuances, secure reliable capital, and execute high-yielding deals with total confidence.
Semi-Commercial lending with LendInvest
Based on feedback from brokers throughout England, Scotland and Wales, we’ve recently expanded our buy-to-let range with a semi-commercial proposition.
- Loan Range: Scalable funding options from £50,000 up to £2,000,000.
- Unit Caps: Up to 20 individual residential units, with absolutely no cap on commercial units.
- ICR Affordability: Financial viability is assessed using an Interest Coverage Ratio calculated from 125%.
- Property Split: Acceptable as security as long as the residential element is more than 50% of the overall value.
- Flexibility Built-In: Run your business on-site? We can accept related occupiers on a case-by-case basis so you can get the funding your client needs.
As mixed-use assets continue to capture investor focus, semi-commercial property offers a powerful strategy for portfolio expansion. A semi-commercial BTL loan with LendInvest provides intermediaries with a flexible financing tool to help clients scale their holdings, optimise tax efficiencies through favourable SDLT structures and lock in reliable, dual-stream revenue.